Is your rental
property compliant?
Get our free compliance checklist so you can rent your home legally – and avoid fines.


Amidst the backdrop of a cost of living crisis and significant rent hikes, strained relations between landlords and tenants have become palpable in various regions of the country. Acknowledging this, the government has unveiled fresh legislation aimed at modernizing tenancy practices and effectively addressing disputes. However, these reforms are unfolding just as numerous mortgaged buy-to-let investors find themselves financially vulnerable due to pronounced spikes in interest rates.
The research, conducted by esteemed estate agency Savills, unveils a substantial growth trajectory in the private rented sector. This sector, which initially encompassed 1.7 million landlords in 1989, witnessed a remarkable expansion to 4.6 million landlords in the present day. Notably, this upswing can be attributed to the introduction of assured household tenancies, which endowed landlords with enhanced flexibility regarding rents and tenancy terms.
While the foundations for sectoral growth were laid through legislative alterations, the true acceleration materialized in the 2000s. This period saw the proliferation of specialized buy-to-let mortgages, effectively establishing landlord endeavours as a mainstream investment avenue for a significant segment of middle-class British citizens.
However, this promising trajectory faced a temporary setback during the financial upheaval of 2008-09. More recently, the imposition of restrictions on tax relief for mortgage interest payments between 2016 and 2020 also exerted a moderating influence on growth.
As the buy-to-let landscape continues to evolve, landlords are tasked with navigating the intricate interplay of financial dynamics and evolving regulations. The synergy between these elements will undoubtedly shape the future of this critical sector in the UK’s property market.
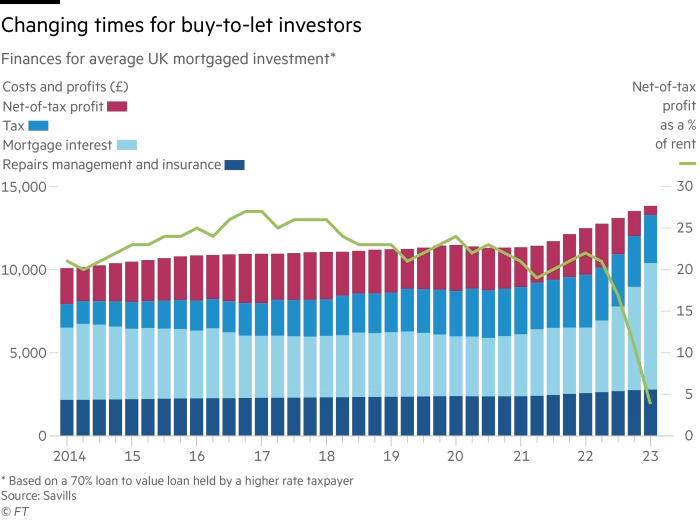
The alteration that removed the ability for individual buy-to-let landlords to offset their mortgage interest expenses against personal tax rates has had profound implications for their bottom line. These ramifications have become increasingly pronounced as interest rates have surged over the past year.
Lucian Cook, the Director of Residential Research at Savills, highlighted a prolonged period during which the restriction of tax relief remained largely inconspicuous due to the prevalence of low interest rates. However, its true impact has only come to light as interest rates have begun to ascend.
Savills cited a compelling scenario: an investor holding a 70 percent loan-to-value mortgage, subject to higher-rate income tax. In the preceding year, a landlord with a property valued at £236,000 would have experienced a respectable profit of 23 percent from their rental income, even after accounting for tax. This figure has now dwindled dramatically to a mere 3.9 percent.
The landscape of buy-to-let mortgages has witnessed a seismic transformation since March 2022, as indicated by financial resource Moneyfacts. Over this period, interest rates have nearly doubled, culminating in significant escalations within the last two weeks. Presently, both two- and five-year fixed-rate mortgages command an average interest rate of 6.03 percent. This stands in stark contrast to the figures of 3.05 percent and 3.29 percent, recorded respectively in March of the preceding year.
In the realm of buy-to-let financing, recent weeks have witnessed pivotal shifts as several lenders recalibrate their rates. Among them, TSB has raised its buy-to-let rates by up to 0.75 percentage points. Similarly, The Mortgage Works, a subsidiary of Nationwide, has adjusted its rates alongside numerous building societies.
As the realm of buy-to-let property investment navigates these turbulent waters, landlords find themselves grappling not only with tax adjustments but also with the evolving landscape of interest rates. This intersection of financial factors necessitates a prudent and adaptable approach to sustain profitability in this dynamic market.
The buy-to-let property market in the UK is in the midst of a significant transformation. The interplay of rising interest rates and forthcoming legislative reforms has prompted landlords to reassess their strategies. While concerns over property sales and supply shortages are palpable, the impact on the market isn’t uniform. As landlords seek ways to maintain profitability, shifts toward cash buyers and limited company structures gain prominence. However, the removal of the Section 21 clause raises concerns about the implications for lower-income households seeking rental accommodation. In this evolving landscape, landlords must navigate changing dynamics, balancing profitability with societal responsibilities.
Click here to read more about section 21 and what it potentially means for youAt Intra Capital Estates, we understand the complexities of being a landlord and are committed to supporting landlords in navigating these changes. Our team of experienced professionals is here to assist you with expert advice, tailored solutions, and comprehensive property management services.
If you have any questions or would like to learn more about the insurance for landlords, or our range of services, we invite you to get in touch. Our dedicated team is ready to address your inquiries and provide the assistance you need to thrive in the evolving rental landscape.
Stay informed, stay proactive, and let Intra Capital Estates be your trusted partner in the ever-changing world of property management.
Please note that the information provided in this blog post is intended for general guidance purposes only and should not be considered as legal advice. Visit gov.uk for more information.
Get our free compliance checklist so you can rent your home legally – and avoid fines.
Want to discuss something more specific? Contact us, and we will be more than happy to help you.
"*" indicates required fields


The eviction process has changed significantly in 2026 – Section 21 has been abolished, and all London landlords now need to use Section ...

The new Renters’ Rights legislation has now passed, bringing major reforms to the private rented sector in England. These changes will di...

Central London’s urban density can make it challenging to keep mice, rats or the dreaded bed bugs away. Private landlords are responsible...


